CRD VI, final act: the last building block of the prudential framework
Directive (EU) 2024/1619 (hereinafter, “CRD VI”) strengthens the European banking regulatory framework across six key areas:
- access to the Union market by institutions from third countries and the regime applicable to their branches;
- the integration of environmental, social and governance risks (hereinafter, “ESG”) into risk management;
- the strengthening of internal governance and fit & proper requirements;
- the prudential framework governing acquisitions, significant transfers, mergers and divisions;
- the evolution of the prudential regime applicable to Class 1 investment firms; and
- the extension of banking supervisory authorities’ powers of supervision and sanction.
Procedurally, CRD VI was to be transposed no later than 10 January 2026. Its transposition is based on Ordinance No. 2026-255 of 8 April 2026 (hereinafter, the “Ordinance”), supplemented by Decree No. 2026-309 of 24 April 2026 and the Order of 29 July 2026. This framework applies to credit institutions, certain investment firms (“class 1” and “class 1 bis”), financial holding companies (including mixed financial holding companies) and financing companies.
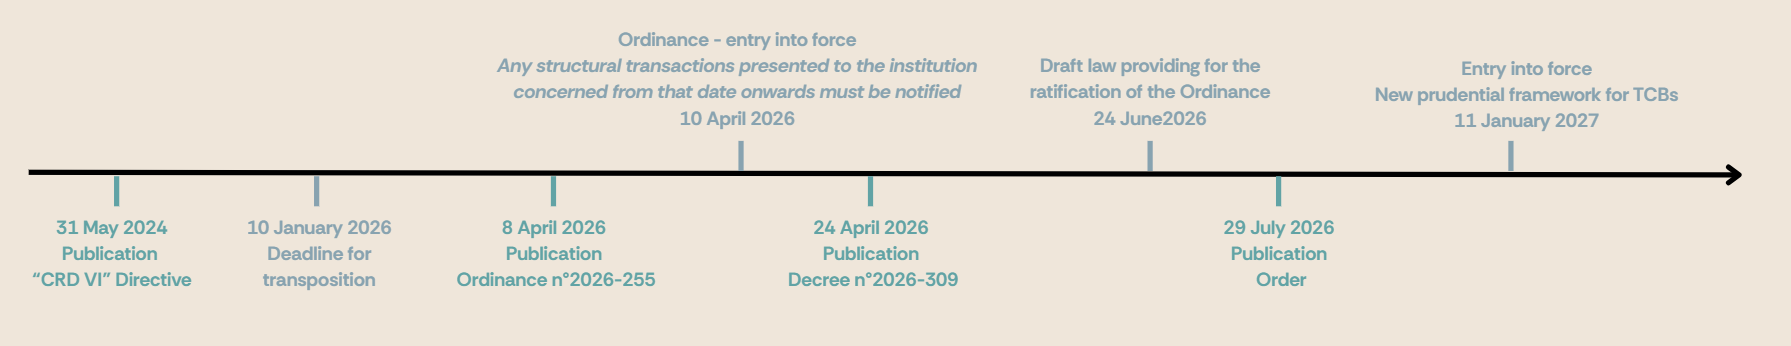
The transposition of CRD VI entails several concrete adjustments for the institutions concerned.
1. CLARIFICATIONS REGARDING THE PROVISION OF BANKING SERVICES FROM A THIRD COUNTRY
1.1 The legal recognition of reverse solicitation
The Ordinance upholds the principle whereby a credit institution established in a third country must operate through a branch duly authorised in France in order to provide banking transactions to clients established or residing in France, subject to exemptions for interbank and intragroup transactions and for those carried out solely at the initiative of the client (reverse solicitation), without any canvassing or marketing by the third-country institution. This latter exemption, now recognised by statute, does not constitute a general market access regime: the institution must document the client’s initiative and demonstrate that it has not actively solicited the business relationship.
1.2 A new prudential regime for branches of credit institutions from third countries (hereinafter, the « TCBs »)
TCBs will need to anticipate their classification under the new prudential regime applicable as from 11 January 2027. Article L. 511-41 of the French Monetary and Financial Code (hereinafter, the “MFC”) replaces the principle of alignment with the requirements applicable to credit institutions with a standalone regime, as specified by the Order of 29 July 2026 amending a previous Order of 11 September 2015. Existing TCBs will be required to provide the Autorité de Contrôle Prudentiel et de Résolution (the “ACPR”) with information demonstrating their ability to comply with this new regime by no later than 10 November 2026. The regime distinguishes between two categories based on the size of the branch, the receipt of funds from non-professional clients and the regulatory framework of its home country, and determines, in particular, the minimum level of required capitalisation.
A branch falls within Category 1 where the total value of its assets reaches EUR 5 billion, or where the repayable funds from the public that it collects from non-professional clients reach 5% of its total liabilities or EUR 50 million, or where it is not eligible having regard to the regulatory and supervisory framework of its home country (a country recognised as equivalent by the European Banking Authority (hereinafter, the “EBA”) and not included on the list of high-risk countries in the area of anti-money laundering). The classification will determine the applicable requirements.
The regime applicable to TCBs is furthermore strengthened: in the event of systemic importance or significant risk, the ACPR may impose a restructuring of assets or activities, additional prudential requirements, or even require conversion into a subsidiary. It may also, on the basis of criteria established by ministerial order, apply the full prudential regime applicable to credit institutions to TCBs. TCBs do not benefit from a European passport: a branch authorised in France is therefore not permitted to provide banking services freely in the other Member States.
2. ENHANCED INTEGRATION OF ESG RISKS INTO INTERNAL FRAMEWORKS
The reform requires credit institutions, financing companies and financial holding companies to integrate ESG risks into:
- their governance;
- their risk management; and
- their loss-absorption framework, in the short, medium and long term, with a time horizon of at least ten years for the latter.
They will be required to draw up prudential transition plans accompanied by quantifiable targets, to integrate these risks into stress tests, and to align their remuneration policy with their ESG risk appetite. However, TCBs authorised as credit institutions are excluded from these obligations.
The board of directors will be required to approve and regularly review the corresponding strategies, and the governance bodies must collectively possess the necessary expertise to understand the impact of ESG factors, this latter obligation being extended to investment firms.
Finally, supervisors will be able to assess these arrangements, including the transition plans, and to require risk-mitigation measures.
3. NEW INTERNAL GOVERNANCE AND APPOINTMENT NOTIFICATION REQUIREMENTS
3.1 With regard to credit institutions, financing companies and financial holding companies
From an internal governance perspective, institutions will be required to formalise responsibilities and adapt their appointment procedures. The reform establishes two new categories of positions:
- “key function holders”, who have a significant influence over the direction of the institution, in particular the chief financial officer and heads of internal control functions, whose suitability will have to be assessed;
- “senior management”, those natural persons who exercise executive functions, are responsible for day-to-day management and are directly accountable to board members, the CEO, deputy CEOs or other effective managers.
Institutions shall be required to keep up to date individual statements and a mapping of duties and responsibilities, in particular those of these two categories of persons.
The reform prohibits the combination of the functions of chair and chief executive officer, thereby removing the possibility of any derogation and extends the simplified notification procedure already applicable to directors to the renewal of executives: only changes liable to affect their fitness shall be required to be notified.
3.2 In respect of large institutions
Large institutions shall, moreover, be required to notify ex-post the appointments of the chief financial officer and the persons responsible for the risk management, compliance and internal audit functions.
The initial appointments of chief executive officers, deputy chief executive officers and chairpersons of the management body shall be subject to prior notification, at least thirty working days before taking up their duties, enabling the supervisor to prepare its assessment without constituting prior authorisation.
4. PRUDENTIAL SUPERVISION EXTENDED TO STRUCTURING TRANSACTIONS
For structural transactions, institutions shall identify the necessary notifications and authorisations as early as the preparation of the transaction timetable.
The new regime covers significant shareholdings, material transfers of assets or liabilities, as well as mergers and divisions. The thresholds are set at:
- 15% of the eligible own funds of the acquirer for shareholdings; and
- 10% of the transferor’s assets or liabilities increased to 15% for intragroup transactions, for transfers of assets and/or liabilities.
The supervision concerns prudential requirements and risks of money laundering or terrorist financing and may be cumulative with the regime applicable to qualifying holdings: the same transaction may therefore require several procedures, the respective time limits of which must be anticipated.
5. POSSIBLE DEROGATION FROM THE BANKING LICENCE REQUIREMENT FOR INVESTMENT FIRMS
Investment firms approaching the thresholds of Class 1 may consider applying for an exemption from the credit institution authorisation, by substantiating the group’s organisation, activities and associated systemic risk. The European Central Bank shall decide on the basis of a proposal from the ACPR, after obtaining the opinion of the EBA issued within one month and shall be required to state the reasons for any departure from that opinion; the decision shall be reassessed every three years.
6. ENHANCED SANCTIONING POWERS OF THE ACPR
CRD VI expands the powers of the ACPR and the scope of persons liable to individual sanctions.
Failure to comply with the specific conditions of an individual decision becomes subject to sanction, and the Sanctions Committee (Commission des Sanctions) may henceforth order an institution to comply with its obligations or to refrain from repeating a breach.
The Sanctions Committee (Commission des Sanctions) may impose suspension or compulsory resignation on key function holders and staff having a significant impact on the institution’s risk profile, and no longer solely on effective managers. Where their personal liability is incurred, it may impose a temporary prohibition on exercising their functions and a pecuniary sanction of up to 5 million euros.
Lastly, the Supervisory Board (Collège de supervision) may attach a penalty payment to its formal notices relating to compliance with the CRR Regulation or with Titles I and III of Book V of the MFC, against credit institutions, financing companies, financial holding companies and class 1 bis investment firms.